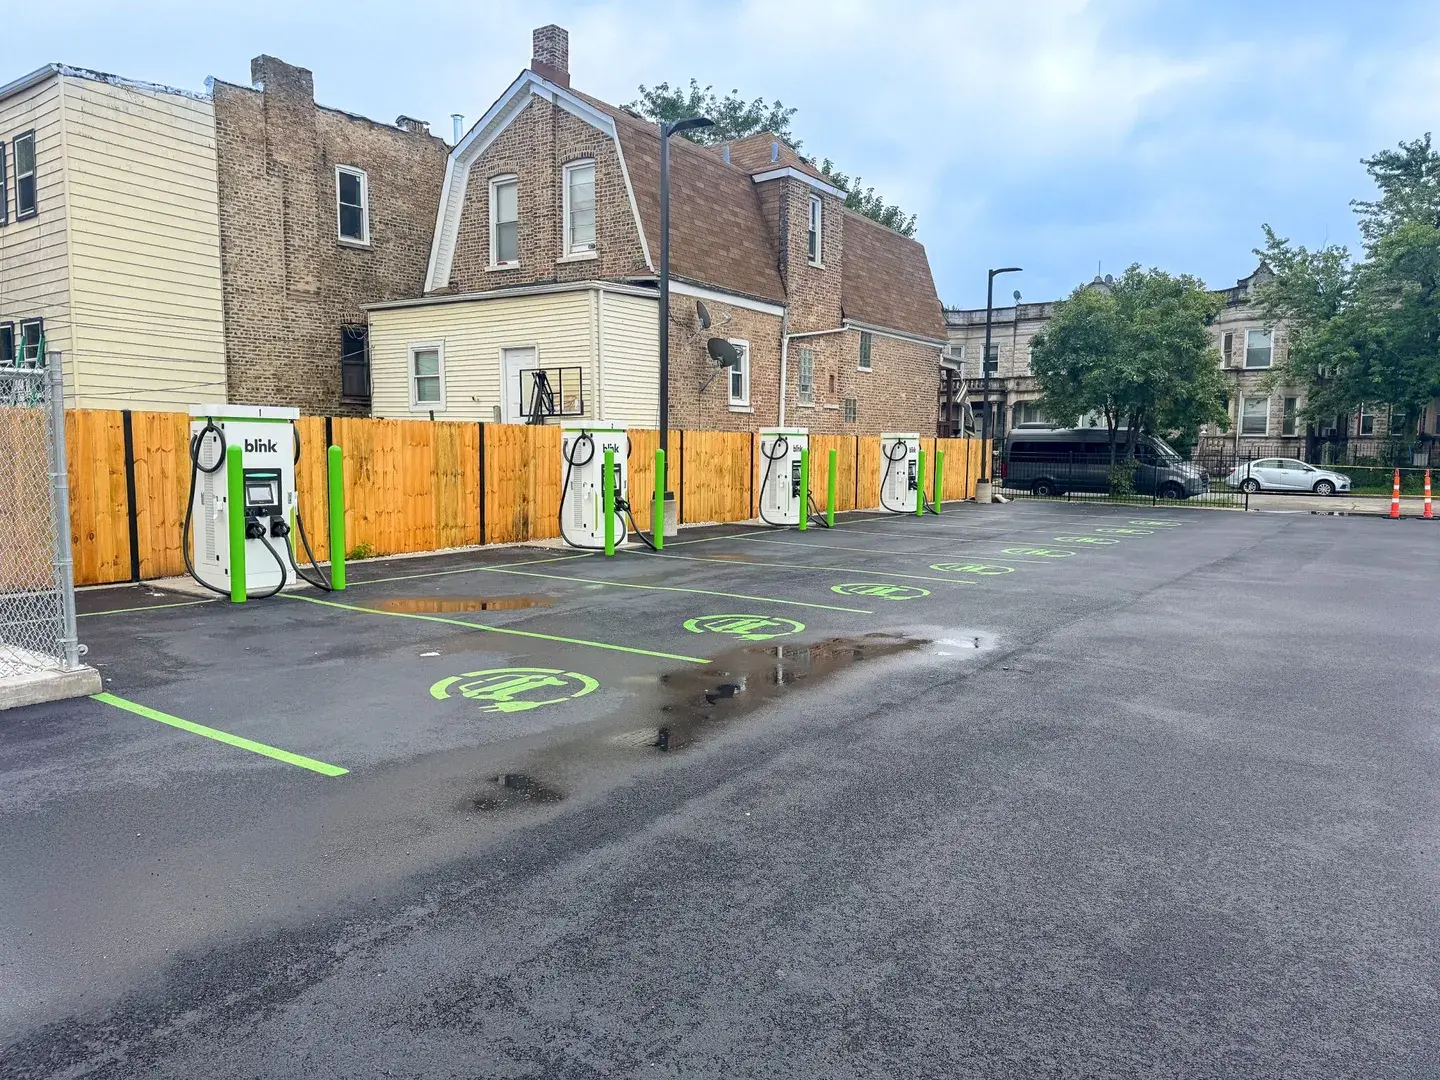
If you came to this page looking for information about the EV charger federal tax credit, the first thing to know is that it expired on June 30, 2026. This incentive is no longer available for new installations, but drivers may still claim it if they installed a qualifying charger before the deadline passed.
Let’s look at what the credit covered, who qualified, how much it was worth, and which incentives can still help reduce the cost of installing an EV charger today.
What Was the Federal EV Charger Tax Credit?
The Alternative Fuel Vehicle Refueling Property Credit gave eligible individuals and businesses a federal tax credit of up to 30% of qualified EV charger installation costs, with a maximum $1,000 credit for personal-use installations.
Commonly referred to as the Section 30C credit, it encouraged the installation of electric vehicle charging infrastructure across the United States. Congress created the incentive years earlier, but it was expanded and reauthorized through the Inflation Reduction Act (IRA) of 2022. Taxpayers claimed the credit using IRS Form 8911 when filing federal income tax returns.
The federal tax credit for EV chargers included separate rules for personal and commercial installations. The credit covered 30% of eligible costs, up to $1,000 per charging area, for homeowners. These chargers had to be installed at the owner's primary residence in an eligible census tract.
Commercial installations qualified for a 6% base credit; this credit increased to 30% if prevailing wage and apprenticeship requirements were met. Commercial credits maxed out at $100,000 per charging system.
Eligible costs generally included:
EV charging equipment
Installation labor
Electrical wiring
Conduit
Electrical panel upgrades required for the charger
Installation expenses directly related to the project
The program also supported organizations traditionally left out of federal tax credit programs. Through the IRA's elective pay, or direct pay, provisions, tax-exempt entities such as nonprofits, schools, Tribal governments, and municipalities could receive the credit, even without federal income tax liability.